Performance audit in university libraries is an essential evaluative process aimed at assessing the efficiency, effectiveness, and economy of library operations and services. Unlike financial or compliance audits that focus on accounting accuracy and policy adherence, a performance audit examines how well the library utilizes its resources- human, financial, and technological- to achieve its institutional objectives. For example, it may evaluate whether a library’s investment in a new digital database has led to increased usage among faculty and students or whether the staffing levels in circulation and reference services are adequate to meet user demand. It serves as a diagnostic tool that helps identify strengths, weaknesses, and areas requiring improvement in the library’s management and service delivery.
In the context of higher education, university libraries play a pivotal role in supporting teaching, learning, and research. Therefore, ensuring that library activities align with the university’s academic goals is of utmost importance. A performance audit systematically reviews various functional areas such as collection development, information access, user satisfaction, technological infrastructure, staff productivity, and financial management. For instance, during a performance audit, a library might assess how effectively its collection development policy meets current academic program needs or whether the online catalogue (OPAC) provides seamless access to both print and electronic resources. Similarly, an audit might evaluate user satisfaction through surveys or feedback forms to determine the quality of reference assistance or Wi-Fi connectivity in study areas.
Conducting regular performance audits enables library administrators to make data-driven decisions, allocate resources more judiciously, and maintain accountability to stakeholders. For example, an audit report might reveal that certain underused journal subscriptions can be discontinued to free funds for purchasing e-books or enhancing digital infrastructure. It also encourages continuous improvement by setting measurable performance indicators and benchmarking against best practices- such as comparing the library’s circulation rate, database usage, or information literacy program outcomes with similar universities. Moreover, in an era of digital transformation, performance audits provide valuable insights into how libraries adapt to technological changes, manage electronic resources, and maintain service quality in hybrid learning environments. For instance, a library might review the effectiveness of its institutional repository or the responsiveness of its AI-based chat support service for remote users. Such evaluations ensure that technological investments truly enhance user experience and academic productivity.
Meaning of Performance Audit in the Context of University Libraries
A performance audit in the context of university libraries refers to a systematic and objective examination of how effectively and efficiently a library utilizes its available resources to achieve its goals and fulfill its academic mission. It goes beyond financial accountability to focus on the three key dimensions of performance- economy, efficiency, and effectiveness. In simple terms, a performance audit evaluates whether the library is doing the right things (effectiveness), doing them well (efficiency), and doing them at the right cost (economy).
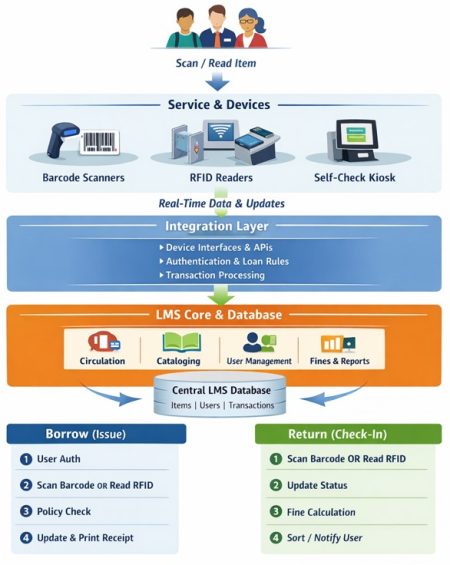
In a university library setting, this type of audit assesses various operational and service areas, including collection development, resource utilization, staff productivity, user satisfaction, technological adoption, and service delivery quality. For example, auditors may examine whether the library’s budget is being used wisely to build a balanced collection that meets current academic and research needs or whether digital subscriptions are generating sufficient user engagement. It also involves assessing whether library staff are appropriately trained and whether technological systems- such as integrated library systems, digital repositories, or RFID services- are functioning optimally to support user needs.
A performance audit provides evidence-based insights into how well the library supports teaching, learning, and research within the university. Unlike routine assessments or internal evaluations, it uses established performance indicators and benchmarks to measure the library’s outcomes against its strategic objectives and comparable institutions. The findings help library administrators identify gaps, eliminate inefficiencies, and enhance accountability.
Why Conducting a Performance Audit is Essential for University Library Management
Conducting a performance audit is essential for university library management because it provides a comprehensive evaluation of how effectively the library is fulfilling its mission to support teaching, learning, and research. In an era where libraries are expected to justify their expenditures and demonstrate measurable outcomes, performance audits serve as a strategic management tool that ensures accountability, transparency, and continuous improvement. They help administrators determine whether resources- such as staff time, budgets, and technologies- are being used efficiently to deliver quality services to the university community.
A performance audit allows library management to identify strengths, weaknesses, and opportunities for improvement in different functional areas, including collection development, digital resource management, user services, and infrastructure utilization. For instance, an audit may reveal that certain databases have low usage despite high subscription costs, prompting reallocation of funds toward more relevant resources. Similarly, it might highlight inefficiencies in cataloging workflows, delays in interlibrary loan processing, or underutilization of reading spaces- all of which can be addressed through informed decision-making. Moreover, performance audits enable libraries to align their objectives with institutional goals. Universities aim to enhance research output, academic excellence, and student satisfaction- objectives that depend heavily on an effective library system. By conducting regular performance audits, library managers can ensure that their policies, services, and technologies are strategically supporting these broader academic missions. For example, audit findings may guide the introduction of new digital literacy programs, extended service hours, or the integration of advanced search tools to improve research accessibility.
Performance audits also foster a culture of evidence-based decision-making and accountability within the library. They provide concrete data and measurable indicators- such as cost per use, user satisfaction scores, or staff productivity metrics- that help justify budget requests and support institutional reporting. Furthermore, they build trust with university stakeholders, demonstrating that the library is managing public or institutional funds responsibly and striving for operational excellence.
How Often Should Performance Audits Be Conducted in University Libraries?
The frequency of performance audits in university libraries is a critical factor that determines how effectively these institutions can maintain efficiency, accountability, and service quality. A performance audit is not a one-time activity; rather, it is an ongoing process that helps library management evaluate operations, monitor progress, and respond to the evolving needs of students, faculty, and researchers. The ideal frequency of conducting such audits depends on several factors, including the library’s size, available resources, technological changes, and institutional policies. However, most experts and library management standards recommend conducting a comprehensive performance audit every three to five years, complemented by annual internal reviews to track progress and address emerging challenges.
Regular audits are essential because university libraries operate in a dynamic environment where user needs, academic programs, and information technologies constantly evolve. For instance, the increasing reliance on digital databases, open-access resources, and online learning platforms requires libraries to continuously assess their technological infrastructure and service delivery models. Conducting performance audits periodically allows libraries to evaluate whether their digital systems, such as integrated library management systems or institutional repositories, are functioning efficiently and providing value to users. A three-to-five-year cycle ensures that library managers have sufficient time to implement previous audit recommendations, observe their outcomes, and make further improvements before the next formal assessment.
In addition to major periodic audits, annual performance reviews play a vital role in maintaining operational accountability. These internal reviews can focus on specific areas such as budget utilization, staff productivity, user satisfaction, or collection development. For example, an annual assessment might analyze database usage statistics or interlibrary loan requests to determine whether current resources align with academic demand. These smaller-scale reviews act as early warning systems, allowing management to detect inefficiencies or declining performance before they become significant issues.
The frequency of audits may also depend on institutional changes or external factors. When a university introduces new academic programs, upgrades its digital infrastructure, or undergoes accreditation, it may be necessary to conduct a special performance audit to ensure that the library is prepared to support these new demands. Similarly, if the library adopts new technologies- such as RFID-based systems, self-check machines, or AI-powered chatbots—an immediate audit can help evaluate their impact on efficiency and user satisfaction. In this way, performance audits remain adaptable and responsive to institutional developments. Moreover, conducting performance audits at regular intervals promotes a culture of continuous improvement. Libraries that routinely evaluate their performance are more likely to innovate, adapt, and maintain high service standards. Regular audits encourage staff to stay engaged, uphold accountability, and contribute ideas for improvement. They also strengthen the library’s ability to demonstrate value and justify budgetary allocations to university administration.
Responsibility for Initiating and Conducting Performance Audits in University Libraries
The responsibility for initiating and conducting performance audits in university libraries typically rests with library administration, working in close coordination with the university’s internal audit office, quality assurance unit, or external evaluation bodies. As the head of library operations, the University Librarian or Library Director plays a central role in initiating the process by identifying the need for evaluation, setting performance objectives, and ensuring that the audit aligns with the library’s strategic goals and institutional mission. The librarian is responsible for preparing the necessary documentation- such as policies, usage reports, and financial records- and for facilitating access to relevant data required for the audit process.
In many universities, performance audits are conducted under the supervision of an internal audit department or a university quality assurance cell (QAC). These bodies ensure that the audit process remains objective, transparent, and compliant with institutional standards. Their role includes forming audit committees, selecting qualified auditors, and determining the scope and methodology of the audit. In some cases, especially in larger institutions, external auditors or consultants specializing in library management and performance evaluation are appointed to provide an independent and unbiased assessment. These external experts bring valuable perspectives by benchmarking the library’s performance against national or international standards.
While auditors are responsible for assessing and analyzing data, the library staff and departmental heads have a crucial supporting role in the process. They provide information about day-to-day operations, respond to queries, and help clarify procedures related to acquisitions, cataloging, digital resources, user services, and staff performance. Their collaboration ensures that the audit findings are accurate, comprehensive, and reflective of actual library practices.
Main Objectives of Conducting a Performance Audit in a University Library
A performance audit in a university library serves as a strategic tool for evaluating how effectively and efficiently the library fulfills its mission to support teaching, learning, and research. Unlike financial audits, which focus solely on fiscal accuracy, performance audits emphasize outcomes, resource utilization, and service quality. They provide a systematic assessment of how well the library’s operations, staff, and resources align with institutional goals. The primary objectives of conducting such an audit include ensuring accountability, improving efficiency, enhancing service quality, aligning library functions with academic priorities, and fostering continuous improvement.
- Ensuring Accountability and Transparency: One of the foremost objectives of a performance audit is to ensure accountability in the management of library resources. University libraries operate using funds allocated by the institution or through public and research grants, making it crucial to demonstrate that every expenditure is justified and beneficial to users. The audit evaluates how budgets are allocated across areas such as collection development, electronic subscriptions, staffing, and technological infrastructure. For instance, if a particular database has a high subscription cost but limited usage, the audit can identify this mismatch and recommend reallocation of funds. This process promotes transparency, ensuring that stakeholders, including university authorities and governing bodies, are confident in how library resources are being managed.
- Evaluating Efficiency and Resource Utilization: Another major objective is to assess the efficiency with which the library uses its available resources. This involves examining whether library staff, facilities, and technologies are being utilized optimally to achieve the best possible outcomes. For example, an audit might review cataloging workflows, circulation systems, or digital service platforms to identify redundancies or delays. By highlighting inefficiencies, the audit helps management make informed decisions, such as introducing automated cataloging systems, implementing RFID-based inventory tracking, or reorganizing staff responsibilities, to improve productivity and service delivery.
- Enhancing Service Quality and User Satisfaction: A key goal of any performance audit is to evaluate and enhance the quality of library services. University libraries exist to meet the diverse information needs of students, faculty, and researchers; therefore, their success depends largely on user satisfaction. Performance audits gather feedback through surveys, interviews, and usage statistics to measure how effectively the library meets user expectations. For instance, an audit might examine access to digital databases, availability of study spaces, responsiveness of library staff, or accessibility of remote services. The findings help library management identify gaps and develop targeted strategies to improve the overall user experience.
- Aligning with Institutional Goals and Academic Priorities: University libraries are integral to achieving broader institutional objectives, such as promoting research excellence, academic success, and innovation. A performance audit ensures that the library’s strategic goals, collections, and programs are aligned with the university’s mission. This includes evaluating whether the library supports new academic programs, provides resources for emerging research areas, and contributes to institutional accreditation requirements. For example, an audit might assess the effectiveness of research support services, information literacy workshops, or institutional repositories that showcase faculty publications. By ensuring alignment with university priorities, the library strengthens its role as a vital academic partner.
- Supporting Evidence-Based Decision-Making: Performance audits provide the data and insights necessary for evidence-based management. The objective here is to equip library leaders with measurable performance indicators- such as cost per use, staff productivity, or user satisfaction ratings—that can guide decision-making. This helps justify budget requests, evaluate new project proposals, and plan for future developments. When decisions are supported by audit findings, libraries can operate more strategically, minimize waste, and optimize their impact within the academic community.
- Promoting Continuous Improvement and Innovation: Finally, performance audits aim to cultivate a culture of continuous improvement. They are not simply tools for identifying weaknesses but also for recognizing strengths and opportunities for innovation. Regular audits encourage libraries to adapt to technological advances, explore new service models, and benchmark their performance against peer institutions. For instance, an audit might recommend adopting AI-powered chatbots, enhancing digital literacy training, or improving open-access platforms. These innovations help the library stay relevant and responsive to the changing information landscape.
In summary, the main objectives of conducting a performance audit in a university library extend far beyond mere evaluation; they are about transformation. Through accountability, efficiency, quality enhancement, alignment with institutional goals, evidence-based decision-making, and continuous improvement, performance audits empower libraries to evolve into dynamic, forward-thinking institutions. They ensure that every investment, every service, and every decision contributes meaningfully to the university’s mission of academic excellence and knowledge advancement.
Areas of Library Operations to Prioritize During a Performance Audit
A performance audit in a university library should focus on key operational areas that directly influence the library’s ability to fulfill its mission of supporting teaching, learning, and research. Prioritizing the right areas ensures that the audit provides meaningful insights into efficiency, effectiveness, and service quality. While the scope of each audit may vary depending on the library’s size, resources, and institutional goals, certain fundamental areas consistently warrant close examination. These include collection development and management, user services, human resources, financial management, technology and digital infrastructure, space utilization, and governance and policy implementation.
- Collection Development and Resource Management: The first and most crucial area to prioritize is collection development, as it forms the foundation of library services. A performance audit should evaluate how effectively the library selects, acquires, and maintains its print and electronic resources. This includes assessing the relevance, currency, and usage of books, journals, databases, and e-resources. For instance, the audit may analyze circulation statistics, cost-per-use data, and subject coverage to determine whether resources align with current academic programs and research priorities. It should also review the library’s collection development policy to ensure that acquisition decisions are transparent, data-driven, and responsive to user needs.
- User Services and Information Access: User services represent the core of library operations, as they directly impact user satisfaction and learning outcomes. The audit should examine areas such as reference and research assistance, information literacy training, circulation services, and access to physical and digital resources. Surveys and feedback mechanisms can be used to measure user satisfaction and identify service gaps. For example, the audit may evaluate how efficiently staff respond to information queries, how accessible e-resources are for remote users, or whether the library’s opening hours meet user demand. Ensuring equitable and seamless access to information resources should remain a key audit priority.
- Human Resource Management and Staff Performance: Library staff are essential to successful service delivery, and their performance significantly influences operational outcomes. A performance audit should review staff workload distribution, professional development, and role effectiveness. It should also assess whether staffing levels are sufficient to support the library’s activities and whether employees possess the necessary skills- especially in digital resource management and user education. For example, the audit might examine training initiatives related to emerging technologies or assess how effectively librarians support academic research and faculty outreach.
- Financial Management and Budget Utilization: Efficient financial management is another critical focus area. The audit should evaluate how the library allocates and utilizes its budget for acquisitions, technology upgrades, maintenance, and staffing. Key questions include: Are funds being spent according to priorities? Are there instances of overspending or underutilization? How does the library ensure cost-effectiveness in subscription renewals and procurement? Financial audits help ensure accountability and transparency while supporting future budget planning based on accurate performance data.
- Technology and Digital Infrastructure: With the increasing digitization of library services, auditing technological infrastructure is essential. The audit should assess the performance of library automation systems, digital repositories, online catalogs, and access platforms such as OpenAthens or EZproxy. It should also evaluate the efficiency of IT support, cybersecurity measures, and user interfaces. For example, assessing the reliability of the library’s website, database access speed, or institutional repository visibility can help identify opportunities for improving digital access and user experience.
- Space Utilization and Physical Facilities: A performance audit should also examine how effectively library spaces are being used. University libraries are no longer only book storage areas- they are active learning environments. The audit may analyze the allocation of study zones, computer labs, reading rooms, and collaborative learning areas to determine whether they meet user needs. For instance, data on foot traffic, occupancy rates, and user feedback can reveal whether existing spaces are underused or overcrowded, prompting decisions on redesign or expansion.
- Governance, Policy, and Strategic Alignment: Finally, the audit should review the library’s governance structure, policies, and strategic alignment with institutional goals. This includes evaluating whether the library’s mission, policies, and performance indicators are consistent with the university’s broader academic objectives. For example, the audit might assess how effectively the library contributes to research output, supports open-access initiatives, or aligns with accreditation requirements.
A comprehensive performance audit should prioritize areas that have the greatest impact on user satisfaction, operational efficiency, and strategic value. By focusing on collection management, user services, human resources, financial control, technology infrastructure, space utilization, and governance, university libraries can gain a holistic understanding of their strengths and areas for improvement. Prioritizing these domains ensures that the performance audit serves as a meaningful tool for enhancing accountability, optimizing resources, and driving continuous growth in academic service excellence.
Methods and Tools Commonly Used in Library Performance Audits
Conducting a performance audit in a university library requires a systematic approach that combines both qualitative and quantitative methods. These methods and tools help assess how effectively the library achieves its objectives, utilizes resources, and delivers services to its users. The choice of method depends on the audit’s scope, available data, and institutional context. Generally, the most effective audits use a combination of data analysis, user feedback, benchmarking, performance indicators, and documentation review to ensure a balanced and comprehensive evaluation.
- Key Performance Indicators (KPIs): One of the most widely used tools in performance auditing is the development of Key Performance Indicators (KPIs). KPIs provide measurable benchmarks for assessing different aspects of library operations, such as resource usage, user satisfaction, cost-efficiency, and service quality. Examples include the number of active users, circulation statistics, database access frequency, cost per use of electronic resources, and reference transaction rates. These metrics help auditors objectively determine how well the library is meeting its goals and where improvement is needed.
- Statistical Data Analysis: Quantitative analysis of library data plays a crucial role in performance auditing. Libraries maintain extensive records through their Integrated Library Systems (ILS) or Library Management Systems (LMS), which provide valuable statistics on acquisitions, circulation, renewals, interlibrary loans, and digital resource usage. Auditors analyze this data to evaluate trends, identify underused resources, and measure cost-effectiveness. For instance, analyzing usage reports from databases or e-journals can reveal whether subscriptions are providing value relative to their cost.
- User Surveys and Feedback Mechanisms: Collecting feedback directly from users is another vital method used in performance audits. Surveys, interviews, and focus group discussions allow auditors to understand user satisfaction, information needs, and perceptions of library services. For example, online surveys can measure satisfaction with study environments, staff assistance, digital access, or reference support. Feedback mechanisms not only highlight areas requiring improvement but also provide insights into emerging user expectations, helping libraries refine their services accordingly.
- Benchmarking: Benchmarking involves comparing the library’s performance with that of similar institutions or established standards. This method helps identify gaps and best practices that can guide improvement. For instance, a university library might compare its collection size, budget allocation, or database usage with peer institutions of similar scale. Benchmarking may also use international frameworks such as the ISO 11620:2014 Library Performance Indicators or standards from professional bodies like the Association of College and Research Libraries (ACRL).
- Document and Policy Review: A thorough review of library documents, policies, and strategic plans is essential during performance audits. This includes examining policy manuals, collection development strategies, user service policies, annual reports, and budget records. The aim is to determine whether policies are being effectively implemented and aligned with the institution’s mission. For example, auditors may assess whether the library’s collection development policy supports new academic programs or whether resource procurement follows institutional financial guidelines.
- Observation and Workflow Analysis: Direct observation of library operations allows auditors to assess how day-to-day processes are carried out. This method helps identify inefficiencies in workflows, such as delays in cataloging, slow circulation processes, or underutilized digital tools. By observing staff performance and user behavior in real time, auditors can gain practical insights into how library services function and how they can be improved.
- Cost–Benefit and Cost-Effectiveness Analysis: Financial analysis tools, such as cost–benefit and cost-effectiveness studies, are also used in performance audits to evaluate the economic efficiency of library services. These analyses determine whether the benefits of certain activities—like database subscriptions, training programs, or technology upgrades—justify their costs. For example, an audit might assess the cost per download for an e-journal to decide if the subscription should be renewed or replaced with open-access alternatives.
- SWOT Analysis (Strengths, Weaknesses, Opportunities, Threats): A SWOT analysis is a qualitative tool often used to summarize the audit findings. It helps library management understand internal capabilities and external challenges. By identifying strengths and opportunities, libraries can leverage their assets for improvement, while recognizing weaknesses and threats enables proactive problem-solving and risk management.
Performance audits in university libraries employ a diverse set of methods and tools that blend quantitative rigor with qualitative insight. Techniques such as KPI measurement, data analysis, surveys, benchmarking, policy review, and SWOT analysis together provide a holistic picture of library performance. When applied systematically, these methods not only help identify areas of inefficiency but also guide strategic planning, resource optimization, and continuous service enhancement. Ultimately, using a mix of these tools ensures that performance audits serve as powerful instruments for accountability, improvement, and innovation in university library management.
Challenges Faced by University Libraries in Implementing Performance Audits
While performance audits are essential for improving accountability, efficiency, and service quality in university libraries, their successful implementation often encounters several practical, organizational, and technical challenges. These challenges arise from limited resources, a lack of expertise, data management issues, and institutional constraints. Understanding these barriers is crucial for designing an effective audit process that produces accurate and actionable results. The major challenges faced by university libraries in conducting performance audits can be grouped into resource-related, organizational, technical, and attitudinal categories.
- Limited Financial and Human Resources: One of the most common challenges is the lack of adequate funding and skilled personnel to conduct comprehensive audits. Many university libraries, especially in developing countries, operate with constrained budgets that barely cover regular operations, leaving little room for specialized auditing activities. Hiring external auditors or consultants with expertise in library performance assessment can be costly. Similarly, internal staff members may not possess the training or experience required to design and execute detailed performance evaluations. As a result, audits may remain incomplete, superficial, or delayed due to resource limitations.
- Lack of Technical Expertise and Training: Effective performance audits require a solid understanding of audit methodologies, performance indicators, data analysis, and reporting techniques. However, many library professionals lack formal training in these areas. Librarians are typically skilled in information management and user services but may not be familiar with auditing tools such as Key Performance Indicators (KPIs), benchmarking standards, or cost-benefit analysis models. Without proper training, data collection and interpretation can become inconsistent, reducing the reliability of audit outcomes.
- Inadequate Data Management Systems: Another major obstacle is the absence of comprehensive and reliable data. Many libraries still rely on fragmented systems for recording usage statistics, acquisitions, or financial transactions. In some cases, older Integrated Library Systems (ILS) do not generate detailed analytical reports, making it difficult to measure efficiency or usage trends. Additionally, data related to e-resources are often scattered across different vendor platforms, complicating centralized analysis. The lack of standardized data collection and storage systems limits the ability to conduct meaningful performance assessments.
- Resistance to Change Among Staff: Human factors often pose significant challenges during performance audits. Library staff may view audits as instruments of fault-finding or criticism rather than tools for improvement. This perception can lead to reluctance, fear, or a lack of cooperation during data collection and interviews. Resistance to change may also occur when audit findings call for restructuring roles, adopting new technologies, or modifying long-standing workflows. Overcoming this challenge requires effective communication, transparency, and a participatory approach that involves staff throughout the audit process.
- Absence of Clear Performance Standards or Benchmarks: Many university libraries lack clearly defined performance standards or benchmarks to measure their success. Without established criteria, such as national library performance standards, ISO metrics, or peer institution comparisons, it becomes difficult to determine what constitutes “good performance.” As a result, audit findings may appear subjective or inconsistent. Establishing clear benchmarks before initiating an audit is essential for ensuring objective evaluation and meaningful interpretation of results.
- Time Constraints and Competing Priorities: Library staff often juggle multiple responsibilities, from user services to digital resource management, leaving little time for extensive data collection and analysis. Performance audits are time-intensive processes that require careful planning, data validation, and follow-up actions. Balancing audit activities with daily operations can lead to delays or incomplete implementation. This challenge is particularly pronounced in smaller libraries where staff capacity is limited.
- Difficulty in Measuring Qualitative Aspects: While quantitative data such as circulation rates and database usage are relatively easy to measure, qualitative factors- such as user satisfaction, learning outcomes, or service impact- are more difficult to quantify. Many libraries struggle to develop appropriate tools to measure intangible benefits like information literacy improvements or research support effectiveness. Consequently, audits may fail to capture the full picture of library performance.
- Limited Institutional Support and Recognition: Performance audits require strong institutional backing to be effective. In some universities, library audits are not given sufficient priority by the administration, or their findings are not integrated into broader strategic planning. Without top-level commitment, audit recommendations may remain unimplemented, reducing their long-term impact. Moreover, if the audit process is seen as a formality rather than a developmental tool, it loses its strategic value.
While performance audits are indispensable for ensuring accountability and continuous improvement in university libraries, their implementation is often hampered by challenges related to resources, data, staff attitudes, and institutional support. Overcoming these obstacles requires a combination of capacity building, leadership commitment, technological investment, and cultural change. Libraries must foster a positive perception of audits- as opportunities for growth rather than criticism- and adopt modern data management systems to facilitate accurate evaluations. With proper planning and institutional collaboration, performance audits can evolve from a challenging process into a powerful instrument for strengthening library effectiveness, sustainability, and academic impact.
Reference Article:
- Khan, B. (n.d.). PERFORMANCE AUDIT OF SOME SELECTED UNIVERSITY LIBRARIES IN WEST BENGAL A FRAMEWORK FOR EVALUATION. Retrieved from: http://hdl.handle.net/10603/201909